Client Education Series
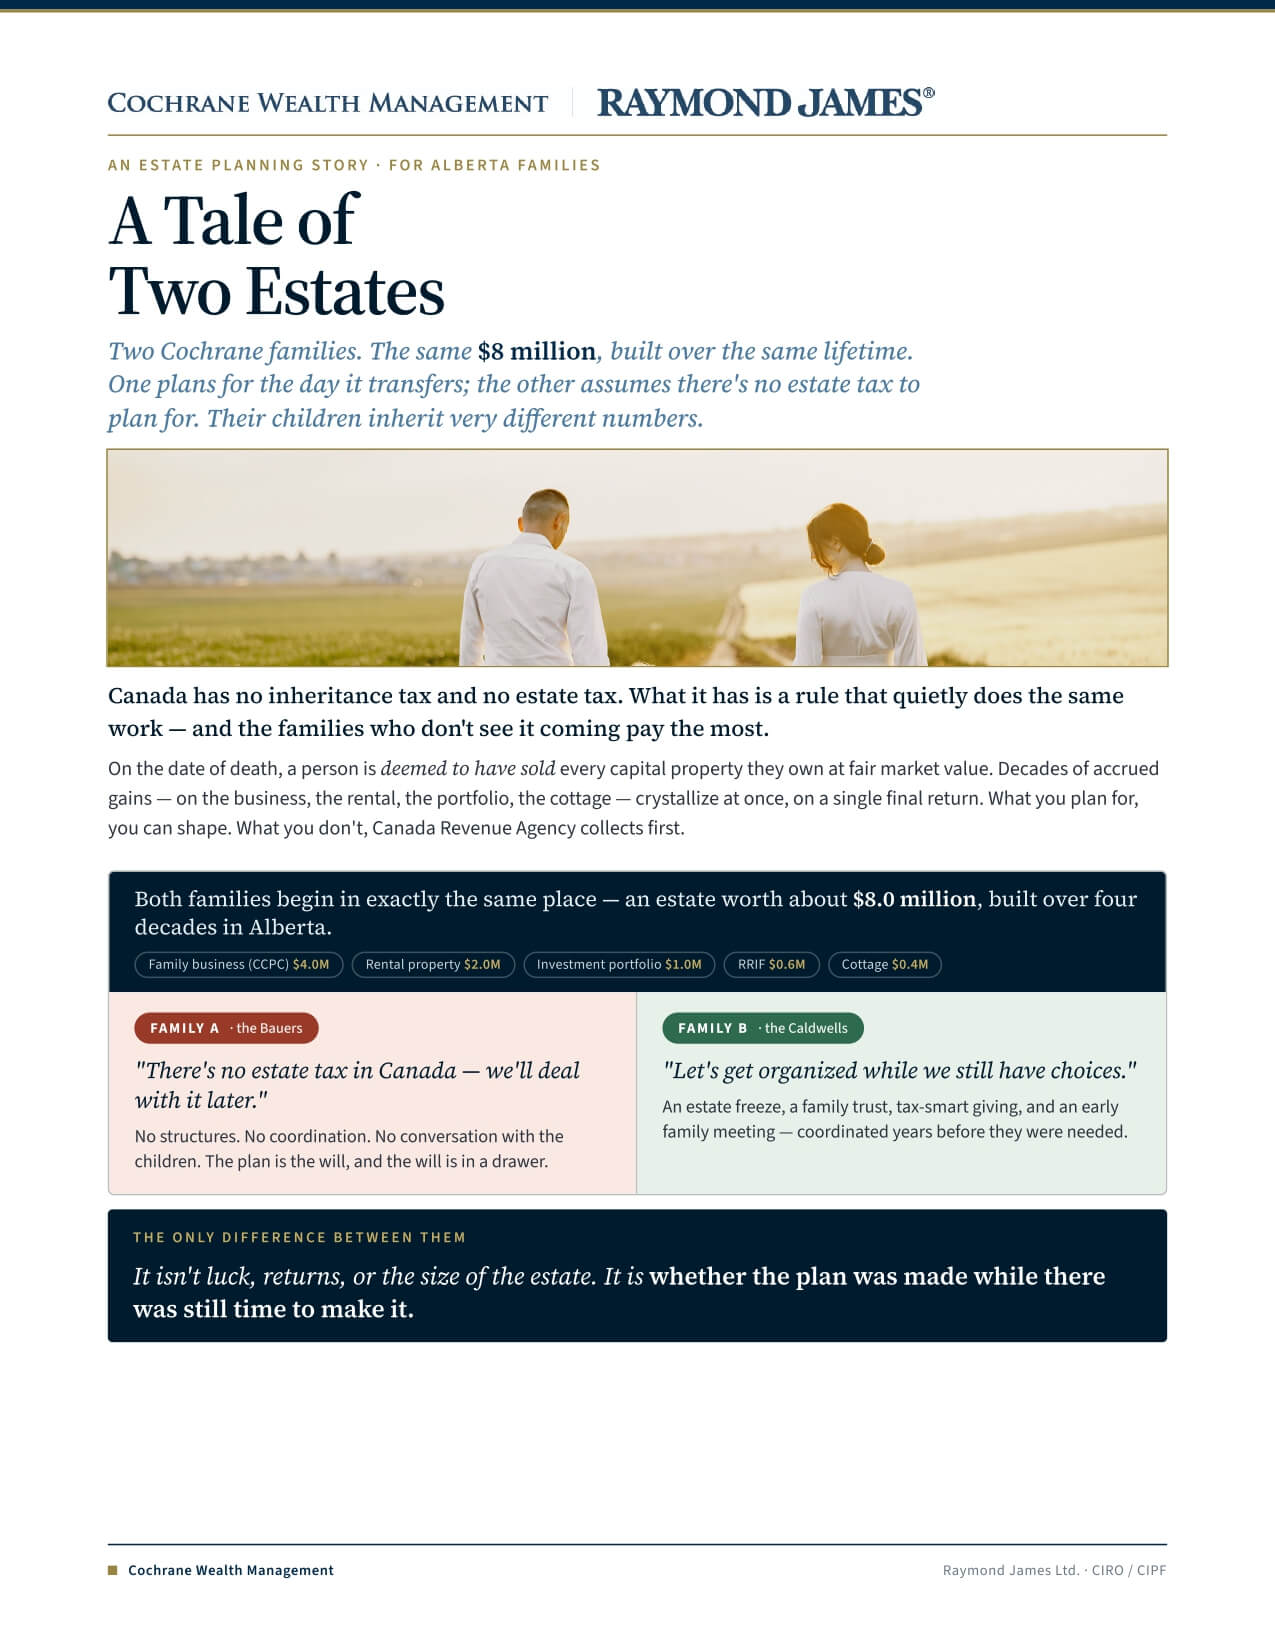
Tale of Two
Estates
Canada has no inheritance tax and no estate tax. What it has is a rule that quietly does the same work — and the families who don’t see it coming pay the most.
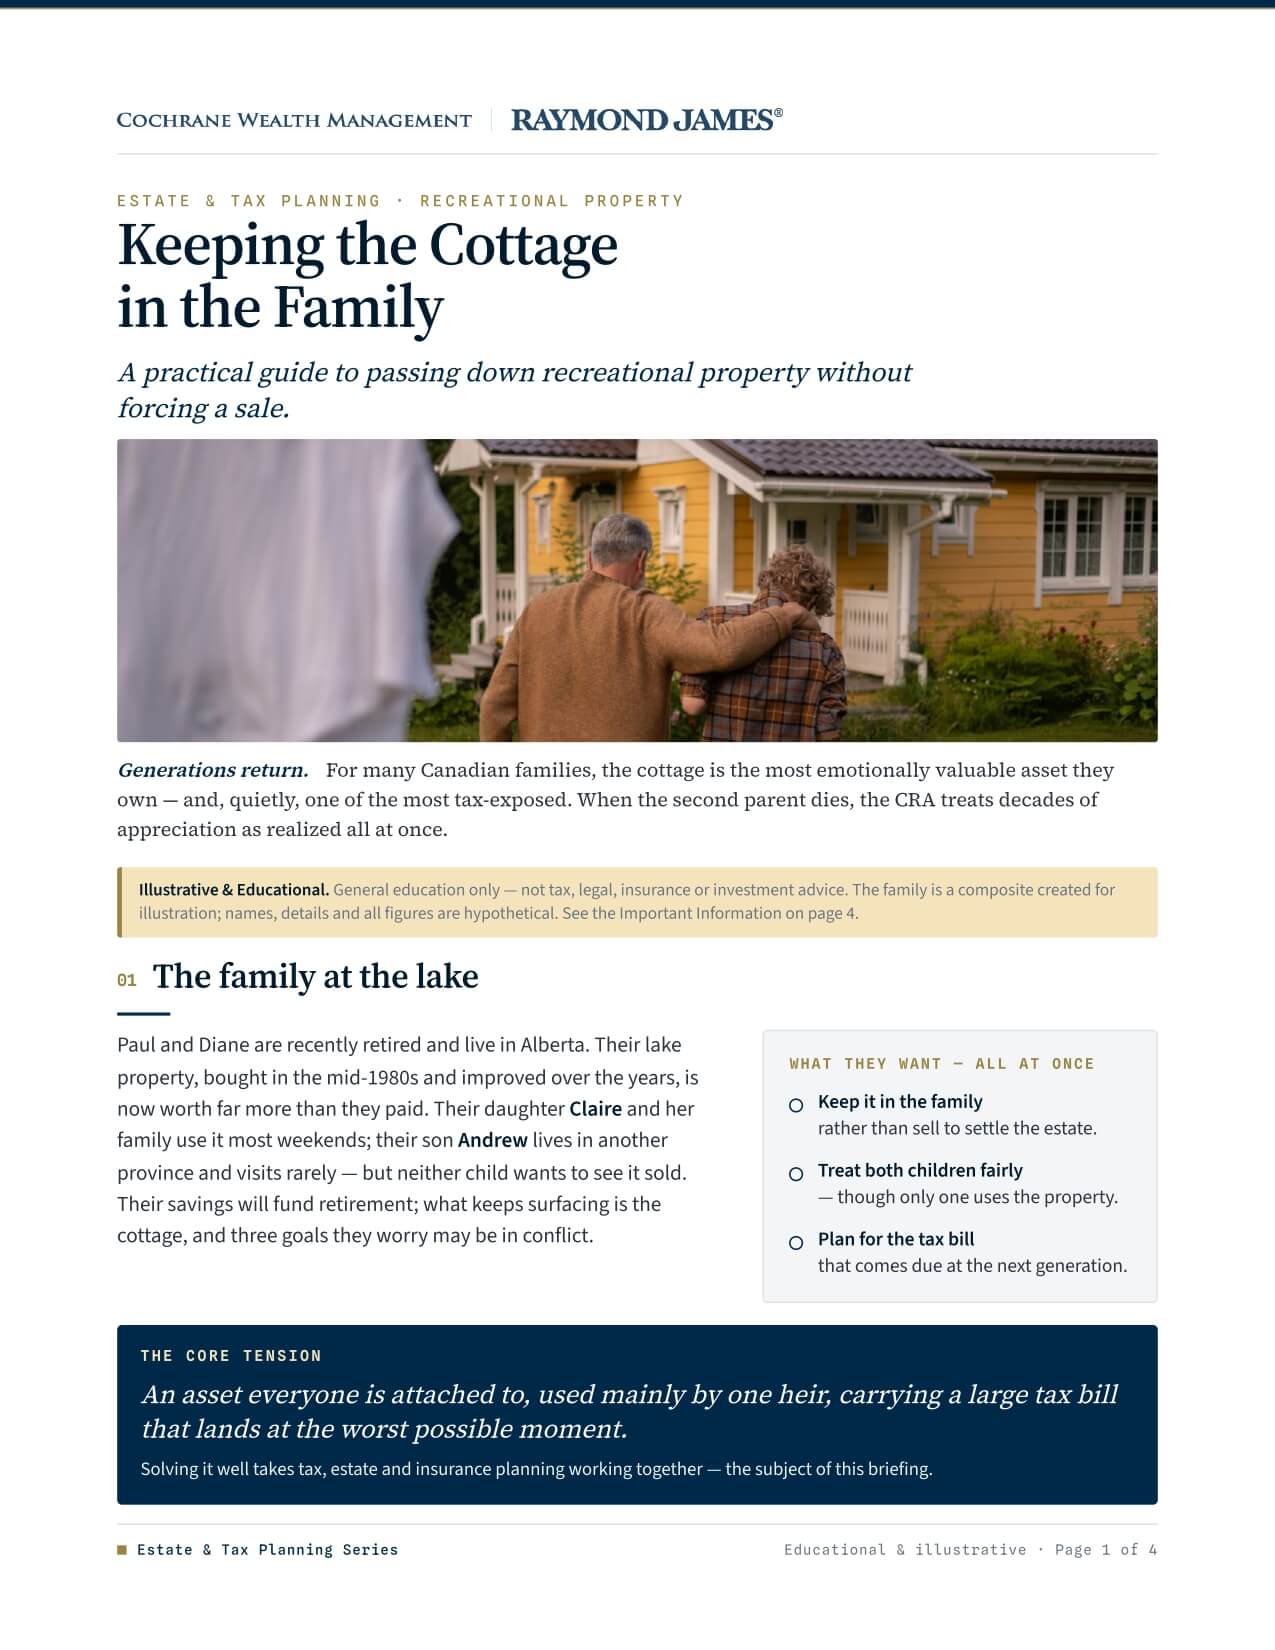
Keeping the Cottage in the Family
For many Canadian families, the cottage is the most emotionally valuable asset they own — and, quietly, one of the most tax-exposed.
The Morning the Offer Came
A buyer’s call is the one date a founder can’t put on the calendar. By the time it arrives, most of the tax has already been decided.
Smarter Accounts, More Wealth
How the right asset in the right account can add thousands per year — without changing what you own.
Same Salary.
Different Down Payment.
Two Alberta engineers, both earning $87,000, both aiming to own a home by 33. Two years later, a single decision is worth more than a year's take-home pay.
Insurance as an Asset Class
How incorporated business owners can shelter retained earnings, grow capital with zero volatility, and pass far more to the generation — without taking on new risk.
From Reactive to Intentional Giving
A structured approach to charitable giving that magnifies your impact, supports tax-efficient planning, and carries your values into the next generation.
Financial Planning in 10 Easy Steps
At its core, sound financial planning comes down to three simple questions. Everything that follows exists to move you from where you are today toward where you want to be.
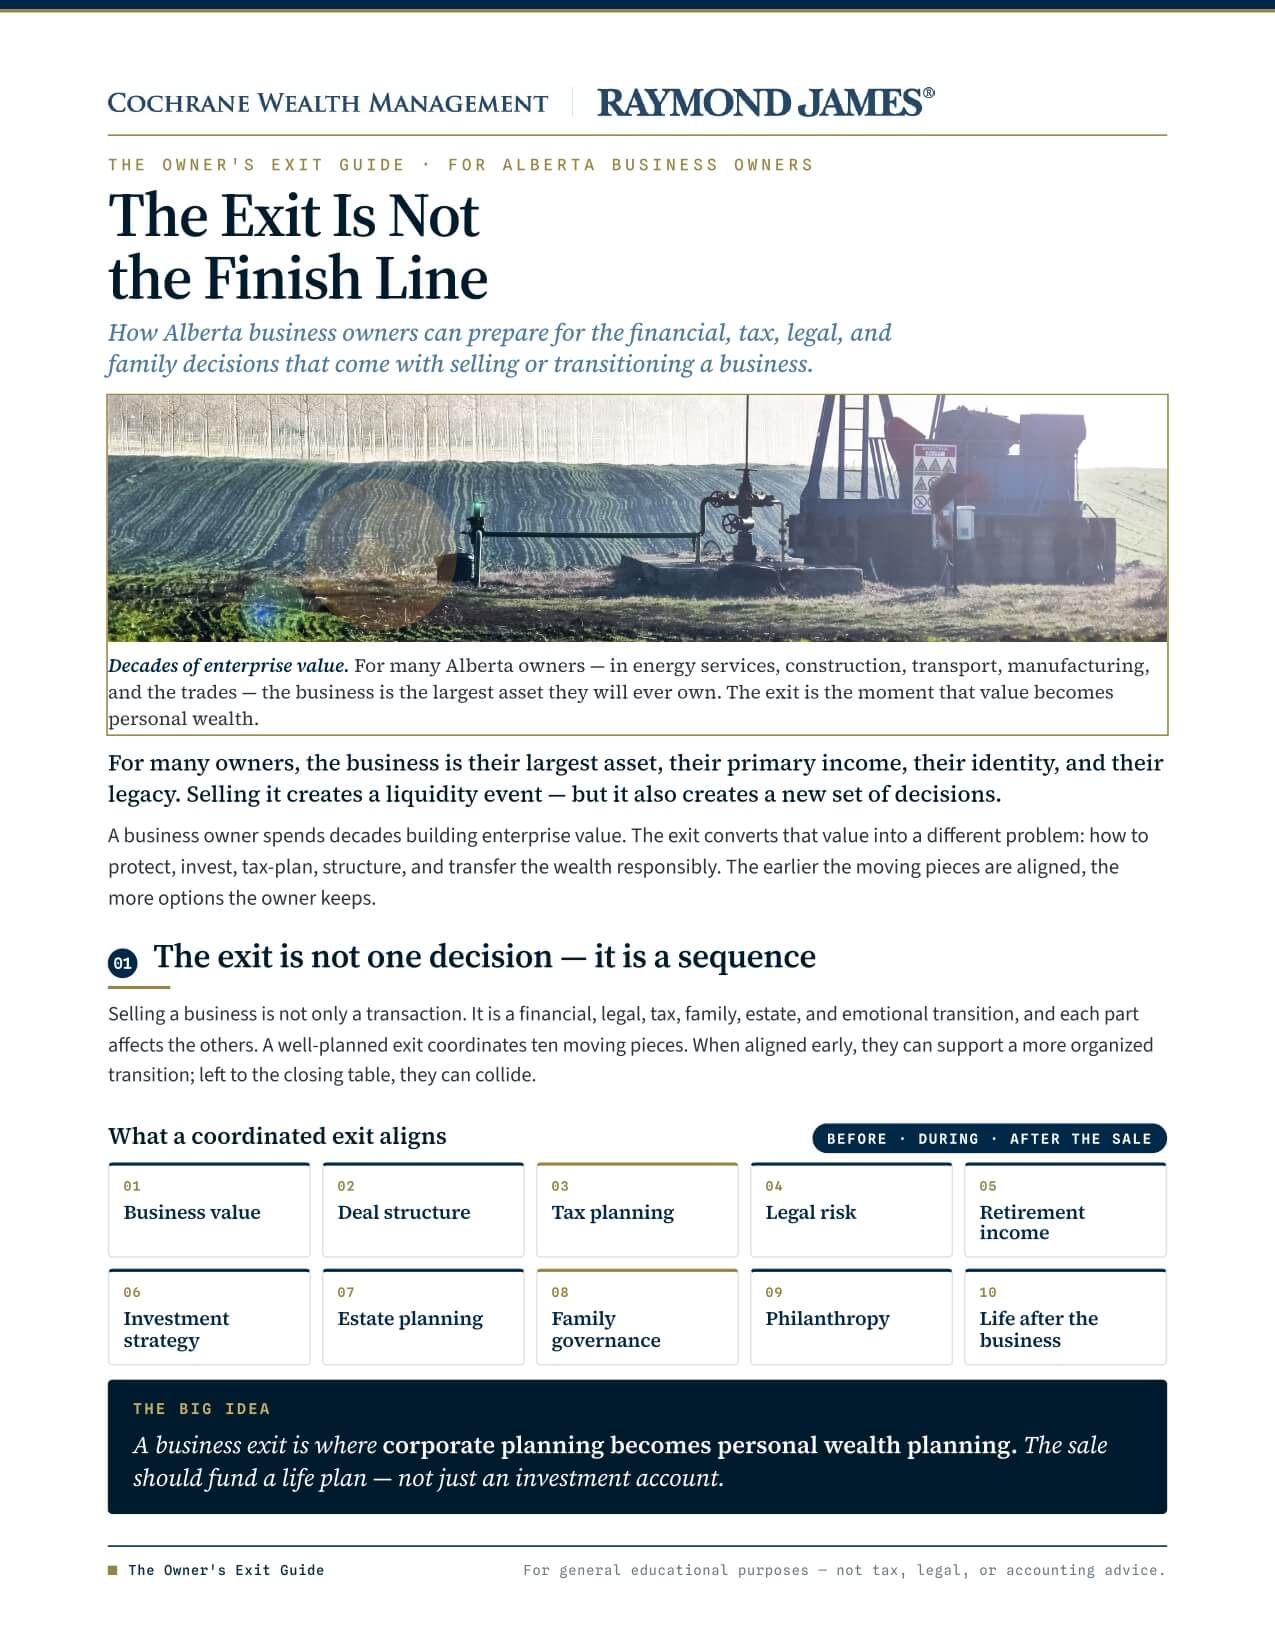
The Exit Is Not the Finish Line
How Alberta business owners can prepare for the financial, tax, legal, and family decisions that come with selling or transitioning a business.